UAE Playbook: Inside the World’s Youngest, Most Vibrant Experiment in Wealth, Safety and Opportunity
How a 54-Year-Old Federation Became a Global Testbed for the Future of Nations
By Kirtiraj Gohil, Founder, PG International Services FZ LLC & Blue Mango Consulting Group (UAE & India)
The United Arab Emirates is only 54 years old as a federation, but it already behaves like a prototype for the next generation of nation-states: hyper-open to talent and capital, relentlessly focused on safety and quality of life, and increasingly serious about a post‑oil, low‑carbon economy.
A country of roughly 11.5 million people, where about 88% are foreign-born and over 200 nationalities live and work side by side, has built non‑oil sectors that now account for more than 70–75% of GDP and achieved a Human Development Index of 0.94, ranking 17th globally and first in the Arab world.
This combination of diversity, safety, and economic reinvention is precisely what many countries say they want to become. The UAE is already doing it—imperfectly, controversially in parts, but at scale.
The rest of the world should study both the playbook and the pressure points.
1. From Desert Sheikhdoms to a Federation: What Actually Happened Since 1971
The modern UAE emerged from a British withdrawal decision and a bold leadership wager on unity.
- In January 1968, Britain announced it would end its treaties and security role in the Trucial States by 1971.
- On 18 February 1968, Sheikh Zayed bin Sultan Al Nahyan of Abu Dhabi and Sheikh Rashid bin Saeed Al Maktoum of Dubai met in the desert and agreed in principle to form a federation—the now-iconic handshake that underpins the UAE’s statehood story.
- On 2 December 1971, Abu Dhabi, Dubai, Sharjah, Ajman, Umm Al Quwain and Fujairah formally created the United Arab Emirates; Ras Al Khaimah joined on 10 February 1972, completing the seven-emirate federation.
- Sheikh Zayed became the first President, Sheikh Rashid the first Vice President and Prime Minister.
From the vantage point of 2025, three phases stand out.
1970s–1980s: State-building on an oil foundation
- Abu Dhabi’s oil revenues funded the first wave of infrastructure: ports, airports, roads, housing, schools, hospitals and federal institutions.
- Jebel Ali Port opened in 1979; it has since grown into the world’s largest man‑made harbour and one of the top 10 container ports globally, handling over 15 million TEU in some years.
- The federation consolidated symbols of sovereignty: a national currency (the dirham), a federal armed forces structure, and membership in the UN and Arab League.
1990s–2000s: Dubai bets on hyper‑connectivity, Sharjah on culture
- Emirates Airline was founded in 1985 and Dubai International Airport later became the world’s busiest for international passengers, handling 92.3 million travellers in 2024.
- Free zones such as Jebel Ali Free Zone (JAFZA) and later Dubai International Financial Centre (DIFC) created enclaves of English‑law‑based, investor‑friendly regulation that attracted regional headquarters and logistics clusters.
- Sharjah doubled down on heritage and education, earning designations as UNESCO Cultural Capital of the Arab World (1998), Islamic Culture Capital (2014) and World Book Capital (2019).
2010s–2020s: From skyline to space, and from oil to clean energy
- Burj Khalifa , completed in 2010 at 828 m, redefined Dubai’s global brand as the world’s tallest building and a symbol of engineering ambition.
- Barakah Nuclear Energy Plant became the Arab world’s first commercial nuclear power station; by 2024 all four reactors were in commercial operation, generating about 40 TWh annually—around 25% of the UAE’s electricity—and avoiding more than 22 million tonnes of CO₂ each year.
- The UAE Energy Strategy 2050 targets clean (renewable + nuclear) energy at 50% of the energy mix by 2050, with a 70% reduction in the carbon footprint of power generation and AED 600 billion in clean‑energy investment.
- The Emirates Mars Mission (Hope Probe) , launched in 2020, entered Mars orbit on 9 February 2021, making the UAE the first Arab and fifth overall entity to reach Mars.
- Expo 2020 Dubai , delayed to October 2021–March 2022 by the pandemic, attracted over 22–24 million visitors and is estimated to generate around AED 122.6 billion in gross value added between 2013 and 2031, supporting nearly 50,000 full‑time-equivalent jobs per year.
- Hosting COP28 in 2023 in Dubai produced the “UAE Consensus”, the first COP decision explicitly calling for a global transition away from fossil fuels, alongside commitments to triple renewable energy capacity and double energy‑efficiency improvement rates by 2030.
Meanwhile, structural reforms have been reshaping the economic model:
- VAT of 5% was introduced in 2018, creating a new non‑oil revenue stream.
- A federal corporate tax of 9% on business profits above AED 375,000 became effective for financial years starting on or after 1 June 2023—still among the lowest headline rates globally.
- Full foreign ownership of onshore companies is now allowed in most sectors under amendments to the Commercial Companies Law and follow‑on regulations.
In less than six decades, the UAE has moved from loose tribal sheikhdoms dependent on pearls and rudimentary oil exports to a diversified, globally connected federation with one of the world’s highest living standards.
2. Seven Emirates, Seven Stories: Trivia That Explains the Country
Behind the single flag are seven distinct economic and cultural propositions.
Abu Dhabi – Capital and energy powerhouse
- Largest emirate by area, holding around 95% of the UAE’s oil reserves and 92% of its natural gas.
- Home to the Barakah Nuclear Energy Plant and major clean‑energy investments under Abu Dhabi’s implementation of the Energy Strategy 2050.
- The emirate is explicitly marketed as home to more than 200 nationalities and a “world‑class quality of life”, reflecting its diverse but relatively high‑income resident base.
Dubai – Global hub of trade, aviation and tourism
- Hosts Burj Khalifa , the world’s tallest building at 828 m.
- Dubai International Airport has been the world’s busiest airport for international passengers since 2014, handling 92.3 million travellers in 2024.
- Jebel Ali Port is the world’s largest man‑made harbour and one of the top 10 container ports globally, with capacity above 20 million TEU and deep integration with JAFZA.
Sharjah – Cultural and educational capital
- Officially designated UNESCO Cultural Capital of the Arab World (1998), Islamic Culture Capital (2014) and World Book Capital (2019).
- Hosts more than 20 museums, major book fairs, and the Sharjah Biennial, anchoring a deliberate strategy to tie economic development to culture and learning.
Ajman – The smallest emirate with outsized ambitions
- The smallest emirate by area at around 260 sq km, with a population just over half a million.
- Known for beaches, mangroves and a growing construction and real‑estate base; Ajman Free Zone and Ajman Port are emerging logistics nodes.
Umm Al Quwain – A window into pre‑oil Gulf life
- Second smallest and least populated emirate, with roughly 49,000 residents in the 2005 census and limited hydrocarbons of its own.
- Economy leans on fisheries, tourism, and the Umm Al Quwain Free Zone; its mangroves and islands (such as Al Seniah) preserve a quieter, less urbanised coastal environment.
Ras Al Khaimah – Mountains, manufacturing and adventure tourism
- Home to Jebel Jais , the UAE’s highest peak at 1,934 m above sea level, now a regional adventure tourism centre with the world’s longest zipline (2.83 km).
- Has been leveraging industrial zones and tourism to diversify beyond its historical role in ceramics and quarrying.
Fujairah – The Indian Ocean gateway
- The only emirate located entirely on the eastern coast along the Gulf of Oman, with about 70 km of coastline and strategic access to Indian Ocean shipping lanes, bypassing the Strait of Hormuz.
- Hosts a major multipurpose port and a large oil storage and bunkering hub, making it central to the UAE’s energy and logistics resilience.
Understanding these micro‑stories matters: the UAE’s model is not one monolithic strategy, but a portfolio of differentiated but complementary city‑states under one federal umbrella.
3. The UAE Model: Radical Openness, Codified Order
A demographic experiment without parallel
- As of 2025, expatriates account for roughly 88–89% of the UAE’s population , with Emirati citizens only about 11–12%.
- The country is home to more than 200 nationalities , arguably the widest such mix worldwide relative to total population.
This is not just diversity by accident, but a strategic design:
- Expatriates make up over 90% of the labour force in some emirates and 96% of employed residents in Dubai.
- Migrants are disproportionately from South Asia (India, Pakistan, Bangladesh), but there are large communities from the Philippines, Egypt, Europe and elsewhere.
The UAE has, in effect, built a global labour market inside a small country.
Connectivity as an economic engine
The openness is grounded in hard infrastructure:
- Air: Dubai International Airport is the world’s busiest airport for international traffic; the broader UAE aviation sector has made the country a natural stopover hub linking Europe, Asia and Africa.
- Sea: Jebel Ali Port is the largest man‑made harbour and a top‑10 container port globally, acting as a gateway to markets of 1.5 billion people across the Middle East, Africa and South Asia.
- East‑coast redundancy: Fujairah’s port and oil storage provide the UAE with direct access to the Indian Ocean, reducing reliance on the Strait of Hormuz chokepoint.
Outcomes: from oil economy to diversified, high‑HDI state
The model has delivered measurable results:
- Non‑oil activities now contribute over 72–75% of UAE GDP , with non‑oil real GDP exceeding AED 1.34 trillion in 2024.
- Sectors such as transport, logistics, financial services, manufacturing and construction have been growing faster than the oil sector in recent years.
- The UAE’s Human Development Index reached 0.94 in 2023 , versus a world average of 0.744, placing it 17th globally and the only Arab country in the top 20.
At the same time, the country is consistently rated among the safest places worldwide:
- Abu Dhabi has ranked as the world’s safest city in Numbeo’s Safety Index every year since 2017 and again in 2024–2025, with safety scores above 88 and extremely low crime indices.
- Multiple UAE cities—Abu Dhabi, Dubai and Sharjah—feature in the global top 5–10 for urban safety in independent rankings.
- At the country level, UAE has topped or been near the top of global safety rankings in 2025.
In short: a heavily migrant, high‑growth, low‑tax, ultra‑safe state is not just plausible—it already exists.
4. Signature Projects That Changed the World’s Perception
Several emblematic initiatives turned the UAE from a regional player into a global reference point.
- Burj Khalifa and Downtown Dubai Burj Khalifa, at 828 m, remains the tallest building on earth and a case study in megaproject execution and urban placemaking.
- Emirates Mars Mission – Hope Probe Launched in July 2020, Hope entered Martian orbit on 9 February 2021, making the UAE the first Arab and fifth overall entity to reach Mars.
- The mission is explicitly framed as a catalyst for Emirati STEM capacity and a symbol of shifting from an oil to a knowledge economy.
- Barakah Nuclear Energy Plant Four APR‑1400 reactors delivering 5.6 GW now supply around a quarter of UAE electricity and avoid over 22 million tonnes of CO₂ emissions annually.
- Barakah is the Arab world’s first commercial nuclear power station and central to the UAE’s Net Zero 2050 pathway.
- Expo 2020 Dubai and Expo City The event attracted over 22–24 million in‑person and virtual visits, supported the recovery of tourism and hospitality post‑COVID, and is estimated by EY and others to generate around AED 122.6 billion in GVA between 2013 and 2031.
- The site is being repurposed as Expo City Dubai , a mixed‑use innovation and sustainability district.
- COP28 Dubai and the UAE Consensus The COP28 outcome for the first time calls on countries to “transition away from fossil fuels” in energy systems, alongside commitments to triple global renewable energy capacity and double energy‑efficiency improvements by 2030.
These projects serve multiple purposes: nation‑branding, diversification, capability building, and signalling to investors and talent that the UAE is playing a long game.
5. Why This Model Is Shaping the Future – And What Others Can Learn
The UAE is not simply “rich from oil”—oil is necessary but not sufficient to explain its trajectory. The underlying design principles matter.
5.1. Open borders for talent, closed borders for disorder
- By allowing migrants to comprise nearly nine‑tenths of the population while maintaining some of the world’s lowest crime rates, the UAE demonstrates that high migration and high public order can coexist —if institutions are designed to do so.
- Strict policing, extensive surveillance and clear consequences for crime coexist with generous economic opportunities and strong public services in health, education and urban infrastructure.
This is controversial in its own right, but it offers a real policy counterexample to narratives that mass migration must inherently erode safety.
5.2. Specialisation and layered regulation
The UAE’s success comes from regulatory layering, not uniformity:
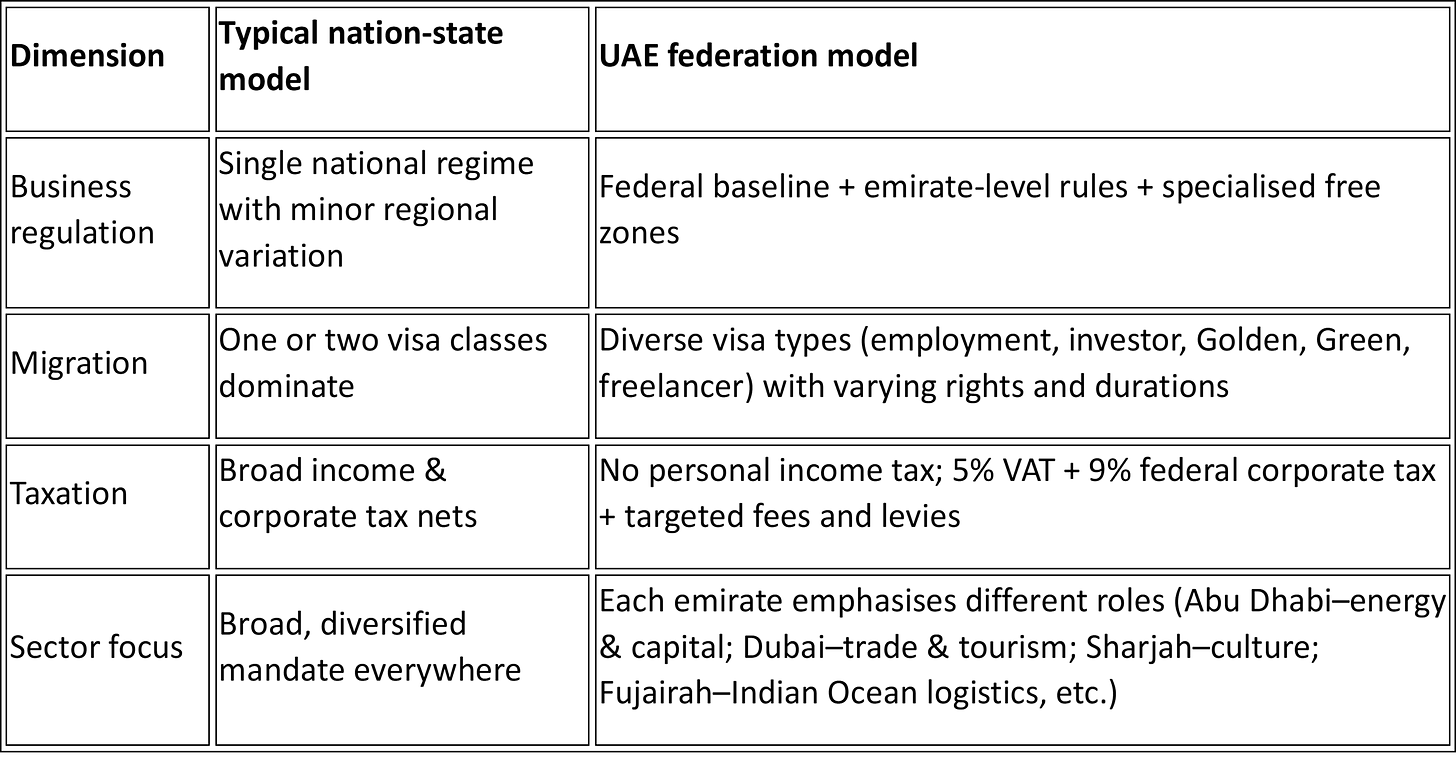
This modularity allows experimentation and competition between emirates and free zones, while the federation still projects a coherent national brand.
5.3. Vision‑driven diversification
Abu Dhabi’s and the UAE’s long‑term strategies—Vision 2030, “We the UAE 2031”, and Energy Strategy 2050—are not merely slogans; they are backed by substantial capital allocations into renewables, nuclear, logistics, tourism, manufacturing and knowledge industries.
The result: non‑oil sectors now drive three‑quarters of real GDP, and sectors like logistics, financial services and manufacturing are expanding faster than hydrocarbons.
For other countries, the transferable lesson is not to copy the UAE’s specific mix of free zones and megaprojects, but to combine:
- Clear long‑term visions
- Credible execution capacity
- Institutional flexibility that allows different regions and sectors to specialise
6. What It Takes to Survive—and Thrive—in Today’s UAE
For individuals and businesses, the UAE’s opportunities come with clear thresholds.
6.1. Financial realities: cost of living and income thresholds
The UAE is no longer a cheap posting. Data from Numbeo and regional analyses show:
- Cost‑of‑living indices for Dubai and Abu Dhabi have risen sharply; Dubai climbed from 138th to around 70th globally in mid‑2024, and Abu Dhabi from 164th to 75th, reflecting rising rents, fuel and imported goods prices.
- In Dubai, a comfortable salary for most expats is typically cited in the range of AED 18,000–30,000 per month , especially for couples or families seeking decent housing, schooling and some savings.
- Analyses suggest that while a single person might “get by” at around AED 6,000–8,000 a month, this usually entails shared accommodation and limited savings.
- For many professionals, average salaries cluster around AED 12,000–20,000 per month, with high‑demand roles in IT, healthcare, financial services and senior management earning well above that.
Must‑haves for individuals:
- A realistic budget that accounts for rent as the largest single expense —mid‑range one‑ or two‑bedroom apartments in Dubai or Abu Dhabi often cost AED 70,000–120,000 per year, plus utilities and cooling.
- Health insurance: mandatory in Dubai and Abu Dhabi, with typical annual premiums ranging roughly from AED 650 for basic coverage up to several thousand dirhams for more comprehensive plans.
- An emergency fund to cover at least 3–6 months of expenses; job loss can rapidly trigger loss of residency if not managed via new employment or updated visa status.
- Awareness of job‑loss insurance schemes (where applicable) that provide limited income support for a few months at modest monthly premiums.
6.2. Legal and employment fundamentals
Recent labour law reforms have shifted the landscape:
- The 2022 labour law requires fixed‑term contracts (typically up to three years), replaces the older unlimited‑term model, and standardises many conditions.
- End‑of‑service gratuity is due after one year of continuous service, generally at 21 days of basic salary per year for the first five years and 30 days thereafter, with reforms removing earlier reductions for resigning employees.
- Employers must pay all end‑of‑service entitlements within 14 days of termination, with substantial fines for non‑compliance.
For professionals, “must‑have” knowledge includes:
- Understanding gratuity calculations and ensuring contracts spell out basic salary and allowances clearly.
- Being familiar with notice periods, probation rules (max six months), and conditions for termination or resignation.
- Keeping copies of contracts, pay slips and communication to support any future labour disputes.
6.3. Skill sets in demand
Data and employer surveys highlight strong demand in:
- Digital & technology: data analysis, AI, cybersecurity, software development, cloud and digital transformation.
- Financial services & fintech: risk, compliance, wealth management, Islamic finance.
- Healthcare & life sciences: doctors, nurses, administrators and allied health professionals, particularly in Abu Dhabi and Dubai medical clusters.
- Logistics, tourism and customer experience: driven by aviation, hospitality, retail and e‑commerce.
Soft skills—cross‑cultural communication, adaptability, and the ability to operate in multicultural teams—are essential in a country where no single nationality is a majority in most workplaces.
6.4. Cultural literacy and compliance
Thriving in the UAE also requires:
- Respect for local laws and norms , including strict regulations on alcohol, public conduct, social media speech, and political expression.
- Awareness that while freedom of worship is protected by law, the UAE remains an Islamic country with expectations around dress and behaviour in public spaces.
- Caution with public criticism: civil society activism, unionisation and public protests are tightly constrained.
7. The Future: Tailwinds, Headwinds and Structural Red Flags
7.1. Structural strengths
- Deepening diversification: Non‑oil sectors already generate over three‑quarters of real GDP and continue to grow faster than hydrocarbons, driven by trade, logistics, real estate, financial services, manufacturing and tourism.
- Clean‑energy investment: The UAE Energy Strategy 2050 targets 50% clean energy in the mix by 2050 and massive efficiency gains; Barakah and large‑scale solar (e.g., Al Dhafra and MBR Solar Park) underpin this shift.
- Policy agility: Rapid introduction of corporate tax, full foreign ownership and new visa categories shows a state apparatus capable of major policy shifts in short timeframes.
- Brand and soft power: Hosting Expo and COP28, investing in space, culture, and humanitarian initiatives, and positioning as a neutral business hub amid geopolitical tensions all strengthen the UAE’s international leverage.
7.2. Economic and fiscal risks
- Residual oil dependence: Despite diversification, hydrocarbons still matter significantly, particularly in Abu Dhabi’s fiscal base; literature on “resource curse” economics underlines the vulnerabilities of oil‑exporting states to price volatility.
- Cost of living and inequality: Rapid increases in rents and living costs—especially in Dubai and Abu Dhabi—risk pricing out mid‑income professionals and exacerbating the gap between high‑earning expats and low‑wage migrant workers.
- Gradual “tax creep”: Introduction of VAT and corporate tax, and movement towards a domestic minimum top‑up tax aligned with OECD Pillar Two, suggest that the long‑term model is low‑tax, not no‑tax .
7.3. Labour and human‑rights concerns
Leading human‑rights organisations and academic work document persistent problems in parts of the UAE labour system:
- Migrant workers—who make up the majority of the workforce—face issues including wage theft, delayed or unpaid salaries, illegal recruitment fees, passport confiscation and exposure to extreme heat, especially in construction and low‑wage services.
- The kafala -style sponsorship system, although reformed on paper, still gives employers substantial control over workers’ ability to change jobs or remain in the country; this has been likened to “modern‑day slavery” by some advocacy groups.
- Workers have limited ability to organise, strike or collectively bargain; labour disputes can result in deportation or loss of legal status, creating a chilling effect on resistance to abusive conditions.
These realities are the shadow side of the gleaming skyline and require continuous reform if the UAE’s model is to remain politically and reputationally sustainable.
7.4. Climate and environmental vulnerability
The Gulf region, including the UAE, is warming roughly twice as fast as the global average, with increasing frequency and intensity of extreme heat events.
- The UAE recorded May temperatures above 50–51.6 °C in 2025, with high humidity pushing dangerous heat indices.
- Research highlights rising risks of water scarcity, food insecurity and heat‑related mortality in the Middle East and North Africa if global warming is not constrained.
- High reliance on energy‑intensive desalination (over 40% of drinking water) and urban coastal development amplifies exposure to both climate and energy shocks.
The UAE is simultaneously a major fossil fuel producer and a leading proponent of net‑zero and clean‑energy strategies; squaring this circle will be one of its defining tests over the next three decades.
8. Red Flags for Professionals, Entrepreneurs and Policymakers
For individual workers and families:
- Residency is still tightly linked to employment or specific visa categories; a lost job can quickly become an immigration problem if planning is weak.
- Social protection is limited: there is no universal unemployment insurance, and pensions for expats depend on private savings and employer end‑of‑service gratuity, which can itself be at risk if employers default.
- Heat stress is a real health threat, especially for outdoor workers; climate trends suggest this will worsen without stringent protections.
For businesses and investors:
- Legal fragmentation across emirates and free zones requires careful structuring and compliance; what is permissible in one zone may not be elsewhere.
- Tax and regulatory regimes are in flux, with corporate tax, domestic minimum top‑up tax and evolving substance rules; investors should assume future tightening, not loosening , on transparency and tax.
- Reliance on low‑wage migrant labour poses reputational and operational risks—especially for companies in construction, hospitality and events—given documented abuses and global ESG scrutiny.
- Climate‑related physical risks (heat, water, coastal exposure) could affect asset values, insurance costs and infrastructure resilience over time.
For policymakers elsewhere, the red flag is different: copying the UAE’s openness without its enforcement capacity, or its labour model without its reform trajectory, could be disastrous.
9. Why the UAE Model Matters on Its National Day
On this UAE National Day, the country stands out not just for what it has built, but for what it is testing on behalf of the world:
- Can a state be majority‑migrant , yet stable and safe? The UAE is proving that it can—though at the cost of a sharply tiered citizenship and labour system.
- Can an oil exporter lead on clean energy and climate diplomacy without fully abandoning hydrocarbons? The UAE is attempting this dual role via Barakah, massive solar, and the UAE Consensus at COP28.
- Can a country transform from resource dependence to knowledge‑ and service‑based prosperity within two generations? Rising non‑oil GDP shares, high HDI, and strong logistics, finance and tourism sectors suggest that it is on that path.
For countries struggling with slow growth, demographic pressure, or polarising debates on migration, the UAE offers a real, data‑rich case study—not a moral template, but a policy laboratory. The right question is not “Should we become like the UAE?” but “Which components of the UAE experiment can we responsibly adapt—and which trade‑offs do we refuse?”
10. In Brief: Key Takeaways
- From handshake to federation: The UAE was formed on 2 December 1971 as a federation of seven emirates, led by Sheikh Zayed and Sheikh Rashid, and has since built robust state institutions and infrastructure.
- Diverse and safe: Around 88% of residents are foreign‑born and over 200 nationalities live in the UAE, yet Abu Dhabi and Dubai consistently rank among the world’s safest cities and the country among the safest globally.
- Economy beyond oil: Non‑oil sectors now account for over 70–75% of real GDP, and the UAE ranks 17th globally on the Human Development Index, first in the Arab world.
- Global projects, global influence: Barakah nuclear plant, the Hope Mars Mission, Expo 2020 and COP28 have positioned the UAE as a testbed for energy transition, space ambition and new forms of diplomacy.
- Opportunities with thresholds: To live comfortably—especially in Dubai and Abu Dhabi—professionals typically need AED 18,000–30,000 per month, robust savings buffers, and a clear grasp of labour law, health insurance and visa rules.
- Serious red flags: Labour rights concerns, climate vulnerability, cost‑of‑living pressures and increasing (though still moderate) taxation are structural risks that individuals, businesses and policymakers must factor into their decisions.
For professionals and firms that understand these dynamics, the UAE remains one of the most compelling places on earth to build, experiment and grow—and one of the most important countries to watch as the world searches for new models of prosperity, diversity and security.
Disclaimer
This article is intended for general informational and educational purposes only and does not constitute legal, financial, tax, or investment advice regarding the United Arab Emirates or any other jurisdiction. Readers should conduct their own research and, where appropriate, seek independent professional advice before making any decisions based on the contents of this article. Facts, figures, laws, regulations, and policies in the UAE may change over time, and no guarantee is given that the information presented is complete, current, or free from error. The views expressed are those of the author and do not necessarily reflect the views of any government entity, organization, or employer. Neither the author nor the publisher accepts any responsibility or liability for any loss, damage, or consequences arising from reliance on the information contained in this article.