INDIA’S AIR CONDITIONER MARKET - The Struggle to Find Momentum
Growth Drivers, Structural Barriers, and Practical Solutions for the Next Phase of Market Expansion
A Research-Based Market Perspective
March 2026
Prepared by Blue Mango Consulting Group
bluemangoconsultinggroup.com
1. The Big Picture: Where India’s AC Market Stands Today
India’s room air conditioner (RAC) market is one of the fastest-growing consumer durables categories in the country. In 2025, retail volumes touched approximately 13.3 million units, a 14% year-on-year jump. Industry forecasts project this will nearly double to 22.5 million units by 2030. The market, valued at roughly USD 6 billion in 2025, is expected to cross USD 20 billion by 2034, growing at a compound annual rate of approximately 15%.
These are impressive headline numbers. But beneath them lies a more complex story.
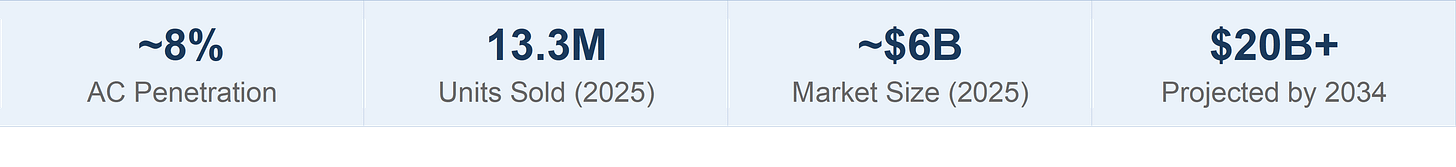
Despite all the growth, India’s household AC penetration hovers around just 8%. Compare that with 90% in Japan and the US, or 60% in China. India has roughly 300 million households. Only about 24 million of them own an AC. The remaining 276 million do not.
This is not a mature market running on replacement cycles. This is a market where the overwhelming majority of potential customers have never owned an air conditioner. The ceiling for growth is massive — but the barriers to reaching it are equally real.
2. The Penetration Paradox: A Market That Should Be Bigger Than It Is
Here is the uncomfortable truth. India regularly records some of the most extreme summer temperatures on the planet. In 2024, Churu in Rajasthan hit 50.5°C. Over 700 heatstroke deaths were reported across 17 states between March and June. The India Meteorological Department issued its first heatwave warning of 2025 as early as April. February 2025 was the hottest February on record.
And yet, ceiling fans remain the primary cooling method for over 90% of urban households and over 80% of rural ones. Fans account for roughly a quarter of total household electricity consumption. ACs, despite all the market excitement, account for only about 6.6% of national electricity demand.
The disparity across states is stark. Punjab has about 70% household AC penetration. West Bengal and Bihar sit at around 5%. Ironically, some of India’s hottest states — Odisha, Jharkhand, Gujarat, Uttar Pradesh, West Bengal, Bihar — have among the lowest penetration rates. That is where the opportunity lies. But it is also where the hardest challenges sit.
Rural AC ownership remains at approximately 1%. The richest 10% of Indian households own the majority of all ACs in the country. This is not just a consumer electronics story. It is a story about economic access, infrastructure readiness, and deeply rooted spending psychology.
3. The Three Growth Engines: Where New Demand Will Come From
3.1 Engine One: New Market Development — Tier 3 and Below
Over 40% of AC demand is now coming from non-metro areas. This is a significant structural shift. For decades, ACs were an urban, metro-city product. That is changing, driven by rising rural and semi-urban incomes, expanded electrification (97% of Indian households now have electricity access), and aspirational consumer behaviour shaped by digital media exposure.
However, there are hard constraints. Two-thirds of rural households and two-fifths of urban households still face at least one electricity outage per day. Voltage fluctuations are common. Many areas in Uttar Pradesh, Jharkhand, Assam, and Bihar still deal with six or more hours of power cuts daily. You cannot sell someone an AC if their power goes out for half the day, or if unstable voltage will damage the unit within months.
Distribution is the other bottleneck. Voltas, the market leader with roughly 20% share, has about 24,000 retail touchpoints nationally. That sounds large — until you realise India has over 640 districts and around 600,000 villages. Getting a split AC into a Tier 4 town, finding a technician for installation, and ensuring after-sales service is an entirely different challenge than managing showrooms in Pune or Ahmedabad.
3.2 Engine Two: First-Time Buyers in Tier 1 and Tier 2 Cities
Even in metros and Tier 1 cities, a large segment of households remain first-time AC buyers. These are typically younger, dual-income families who have recently moved into apartments or are upgrading their living standards. They are digitally informed, EMI-conscious, and brand-aware. The availability of no-cost EMI options, exchange programmes, and festive season promotions has reduced the entry barrier for this group.
The challenge with this segment is not awareness. It is cost anxiety. They know about ACs. They want one. But they worry about the monthly electricity bill. They worry about maintenance costs. They worry about stabiliser requirements, installation hassles, and the total cost of ownership. The purchase price of the AC is only one piece of their mental calculation.
3.3 Engine Three: Replacement Demand
India has roughly 110 million room ACs currently in use. A significant portion of these are older, less efficient models. The Bureau of Energy Efficiency (BEE) has introduced stringent new star rating standards effective January 2026, which will raise the efficiency bar considerably. The government’s proposed “AC swap” programme aims to incentivise consumers to replace old, inefficient units with new 5-star rated models through rebates and trade-in offers.
This is a genuine growth lever, but it is slower and more methodical than new buyer acquisition. Replacement cycles in India tend to be long — many households operate ACs for 10–15 years before considering a replacement. The new efficiency standards and awareness campaigns will gradually accelerate this, but it is not going to produce overnight surges.
4. The Three Factors Holding Growth Back
4.1 Reach and Distribution
The current distribution model is fundamentally urban-centric. Most AC brands rely on traditional dealer networks, multi-brand retail outlets, and increasingly, online channels. This works well in metros. It fails in smaller towns and rural areas where consumers want to physically see and touch the product before buying, where installation requires local technicians, and where after-sales service needs to be within accessible distance.
India’s domestic RAC manufacturing capacity is around 24–26 million units and is expected to grow by 40–50% over the next two years. The supply side is ramping up fast. The distribution side is not keeping pace.
4.2 Energy Efficiency at an Affordable Price
The good news: inverter ACs, which consume significantly less electricity than older fixed-speed models, now dominate the market. Their share has grown from just 1% in 2015 to roughly 60% of all sales. BEE’s star labelling programme has been instrumental in driving this shift, with efficiency improving by 43% since the programme launched in 2006.
The challenge: the most efficient models remain expensive. Entry-level inverter ACs start around ₹25,000–30,000 for a 1-ton unit. Premium 5-star models from brands like Daikin, LG, or Hitachi range from ₹40,000 to ₹80,000. For a family in Jhansi or Siwan considering their first AC, these price points are a serious barrier.
A critical tailwind: the GST reduction from 28% to 18% on air conditioners, effective September 2025, has reduced prices by approximately ₹2,000–3,000 per unit. This is meaningful, particularly at the entry level. But alone, it is not enough to convert the vast pool of aspirational non-buyers.
4.3 The “Costly” Perception
This is perhaps the most stubborn barrier. For millions of Indian households, an AC is still mentally classified as a “luxury” item — something for the rich, something that will make the electricity bill unmanageable. This perception persists even when the reality has changed considerably.
A modern 5-star inverter AC running 8 hours a day typically costs ₹1,500–2,500 per month in electricity — far less than the ₹4,000–5,000 that older non-inverter models would consume. But many potential first-time buyers are still basing their expectations on stories from neighbours who ran old, inefficient window ACs a decade ago. The perception is outdated, but it has not been effectively corrected.
The recent reclassification of ACs from the 28% GST slab to the standard 18% slab is a policy acknowledgment that ACs are no longer luxury goods in India. The market’s communication, however, has not caught up with this shift.
5. What the Industry Can Actually Do: Practical Solutions
The structural opportunity is clear. The barriers are equally clear. The question is: what practical steps can manufacturers, distributors, and the broader ecosystem take to convert latent demand into actual sales? Here are specific, actionable approaches.
5.1 Communicate Energy Efficiency as Value for Money — In Rupees, Not Stars
The BEE star rating system is excellent policy. But most consumers do not intuitively understand what “5-star” means in terms of monthly savings. The industry needs to shift from technical jargon to rupee-denominated communication.
Instead of saying “5-star rated, ISEER 4.5”, the messaging should be: “This AC will cost you approximately ₹50 per day to run. That’s less than your daily chai budget.” Or: “Over 10 years, this ₹35,000 AC will save you ₹1.5 lakh compared to an older model.”
Print the lifetime electricity cost comparison directly on the product packaging. Show a simple table at point of sale: old AC vs. new AC, monthly bill comparison. Make it impossible for the consumer to miss the economic argument.
5.2 Build AMC and Extended Warranty Into the Price
One of the biggest anxieties for first-time AC buyers is: “What happens when it breaks?” Repair costs, gas refilling, technician availability — these are genuine worries, especially in smaller towns where qualified service is scarce.
The solution: bundle 3–5 year comprehensive AMC (Annual Maintenance Contract) and extended warranty directly into the purchase price. Do not offer it as an optional add-on. Make it non-negotiable. Price the AC at ₹38,000 instead of ₹34,000, and include everything — annual servicing, gas top-ups, parts replacement. The consumer pays a slightly higher upfront amount but eliminates all uncertainty about future costs.
This directly attacks the “hidden cost” anxiety that deters purchase. It also builds long-term brand loyalty and creates a recurring service relationship with the customer.
5.3 Bundle the Complete Cooling Solution — Not Just the AC
In most Indian homes, buying an AC is not just buying an AC. It also means buying a stabiliser (₹2,000–4,000), potentially an inverter/UPS if power cuts are frequent (₹8,000–15,000), copper piping for installation (₹2,000–4,000), and sometimes even basic room insulation improvements.
The total cost of “getting cool” can be 40–60% higher than the sticker price of the AC itself. This is a major shock for first-time buyers and a common reason for purchase abandonment.
The industry should offer “Cooling Ready” packages — all-inclusive bundles that include the AC unit, stabiliser, installation, basic piping, and a starter AMC, at a single transparent price. Financing this as a single EMI (₹1,500–2,000/month for 18–24 months) makes the decision dramatically simpler and more accessible.
5.4 Create an Alternate Distribution Model: The District-Level Van Demo
Traditional showroom-based distribution will not reach Tier 3, 4, and 5 markets. The costs of establishing and maintaining physical retail in every district town are prohibitive.
An alternative: mobile demonstration vans operating at the district and block level. Branded, air-conditioned vans that travel to mandis, haats (weekly markets), town centres, and housing colonies. Consumers can walk in, experience the cooling firsthand, ask questions, and place orders on the spot with financing options.
This model has precedent. Eureka Forbes built its water purifier business substantially through direct demonstration. FMCG companies regularly use van-based distribution in rural India. Automobile companies run similar experiential campaigns for new launches.
For ACs, the van demo model has a unique advantage: you can let the customer feel the product working. No brochure, advertisement, or online review replicates the experience of stepping into a cool space on a 45°C afternoon. Pair the demo van with on-the-spot EMI approvals (via fintech partnerships), and the conversion path from curiosity to purchase collapses to minutes.
5.5 Additional Practical Solutions
Leverage Self-Help Groups (SHGs) and Cooperative Networks
India has over 90 lakh Self-Help Groups covering nearly 12 crore women members. In rural and semi-urban India, SHGs are trusted institutions. Partnering with SHGs for group purchase schemes — where 10–20 families in a cluster buy together at bulk-negotiated rates with shared installation logistics — can reduce per-unit costs and solve the last-mile delivery problem simultaneously.
Run “Total Cost of Ownership” Calculators at Point of Sale
Place a simple tablet-based calculator at every retail touchpoint. The customer enters their city, room size, and typical usage hours. The tool shows: estimated monthly electricity cost, comparison with an air cooler, comparison with an older AC model, and total 10-year cost. Transparency kills uncertainty.
Partner with State DISCOMs for On-Bill Financing
In many Indian states, electricity distribution companies (DISCOMs) have a direct billing relationship with every household. Partnering with DISCOMs to offer AC purchases through electricity bill EMIs — similar to what EESL has piloted for energy-efficient appliances — removes the need for separate loan applications. The customer’s AC payment becomes a line item on their existing electricity bill, payable over 12–24 months.
Invest in a Trained Installation and Service Network in Tier 3+
No amount of marketing will sustain growth if the installation and service experience is poor. In Tier 3 and smaller markets, the single biggest complaint is inconsistent installation quality and absent after-sales service. Brands that invest in training local technicians, certifying them, and integrating them into a trackable service management system will build a durable competitive moat in these markets. The ITI (Industrial Training Institute) network across India offers a natural pipeline for this.
Build Rental and “Try Before You Buy” Models
For genuinely hesitant first-time buyers, a rental option for the summer season (₹1,500–2,000/month for 4 months) can serve as a risk-free trial. If the customer is satisfied, the rental amount can be adjusted against the purchase price. This converts fence-sitters without requiring them to make a large upfront commitment.
Localise Product Design for Indian Conditions
Indian conditions are distinct: extreme heat (45°C+), high humidity in coastal regions, dusty environments, and frequent voltage fluctuations. Models specifically designed to handle wider voltage ranges (140–280V) without a stabiliser, with enhanced dust filtration, and with tropical compressors rated for 52°C operation, should be marketed as “Made for India” products, not just rebadged global models. This builds trust, especially with first-time buyers wary of buying a product that “may not work here.”
6. The Competitive Landscape: Who Is Positioned Where
The Indian RAC market is intensely competitive. Voltas (Tata Group) leads with approximately 20% market share, having sold over 2.5 million units in FY2024-25 — the highest ever by a single brand. Its strength is deep distribution in Tier 2 and 3 cities and the trust premium of the Tata brand. Daikin holds roughly 18–19% share, leading in premium and inverter technology with aggressive localisation of manufacturing (compressors, PCBs). LG dominates in dual-inverter technology and urban markets. Lloyd (Havells), at around 6–7% share, is the fastest-growing challenger, leveraging Havells’ massive dealer network for Tier 2/3 penetration. Blue Star commands over 14% share with strength across both residential and commercial segments. Samsung is at about 7–8%, pushing AI-enabled features.
Behind these brands, the OEM/ODM ecosystem is equally important. Amber Enterprises alone holds roughly 24% of India’s RAC manufacturing market, supplying to Voltas, Blue Star, Daikin, and others. The PLI (Production-Linked Incentive) scheme is further expanding domestic manufacturing capacity.
For new entrants or challengers, the lesson is clear: winning in India is not just about product specs. It is about distribution depth, service credibility, financing accessibility, and price-point engineering for a market where the average buyer is spending ₹30,000–40,000 on what feels like a significant household investment.
7. The Policy Tailwinds: What Has Changed
Several recent policy developments are structurally favourable for market expansion:
• GST Reduction (September 2025): ACs moved from 28% to 18% GST under the GST 2.0 reforms. This has reduced retail prices by approximately ₹2,000–3,000 per unit — a meaningful nudge at the entry-level price point. • New BEE Star Rating Standards (January 2026): Stricter efficiency thresholds will push manufacturers towards better-performing models and may raise prices by ₹500–2,500 per unit. This will partially offset the GST benefit but accelerate the shift to inverter-only portfolios. • Quality Control Order (QCO): Being implemented in phases, mandating BIS compliance and greater indigenisation of manufacturing. This will squeeze out non-compliant imports and improve overall product quality in the market. • AC Swap Programme: Proposed government scheme offering rebates and trade-in incentives to replace old, inefficient units with 5-star models. If implemented at scale, this can accelerate replacement demand significantly. • PLI Scheme for White Goods: Attracting investment in domestic manufacturing, with capacity expected to grow 40–50% from the current 24–26 million units over the next two years.
8. The Honest Assessment: Why Momentum Remains Elusive
Despite all the tailwinds — scorching summers, policy support, GST cuts, rising incomes, expanding electrification — the AC market’s growth trajectory is not smooth.
FY2025-26 started with a jolt. Industry volumes in Q1 (April–June 2025) declined 25–34% year-on-year due to unseasonal rains and a late-arriving summer. Major players like Voltas, Blue Star, and Havells saw revenue dips. Brands had built inventory based on expectations of 25–30% growth and were caught off-guard. The revised full-year growth expectation settled at 10–15%.
This is the fundamental fragility: the AC business in India remains heavily weather-dependent. A mild April can wipe out months of planning. A good monsoon that cools temperatures early can cut short the selling season. This volatility makes consistent, compounding growth difficult to deliver.
The path from 8% penetration to even 25% will take a decade or more. It will require patience, sustained investment in distribution and service infrastructure, intelligent bundling and financing, and a fundamental shift in how the industry communicates value to the consumer. There are no shortcuts.
9. Conclusion: The Market Is Not a Narrative — It Is a Problem to Solve
The Indian AC market does not need more optimistic forecasts. What it needs is a clearer understanding of why 92% of Indian households still don’t own an air conditioner — and a set of practical, executable strategies to change that reality.
The three growth engines — new markets in Tier 3 and below, first-time buyers in Tier 1 and 2, and replacement demand — are real. But each requires a different playbook. Tier 3+ needs physical presence, demonstration, and trusted service. First-time urban buyers need transparent total-cost communication and hassle-free bundled solutions. Replacement buyers need compelling swap economics and awareness of how much they are overpaying in electricity by holding on to old models.
The brands and ecosystem players that solve these specific problems — not in marketing decks but in actual field execution — will capture the disproportionate share of India’s next phase of cooling demand.
Sources and References
Euromonitor International – Air Conditioners in India (2025); IMARC Group – India Air Conditioning Market Report (2025); ICRA Research – Room AC Industry Analysis (FY2026); Bureau of Energy Efficiency (BEE) – Star Rating Programme Data; CLASP – Increasing Access to Air Conditioners in India (2023, 2025); Renub Research – India Air Conditioner Market Analysis (2025-2033); NFHS-5 Data – National Family Health Survey; Down To Earth – India’s AC Boom Analysis (April 2025); ScienceDirect – Accelerating Room AC Efficiency in India (September 2025); Government of India, PIB – GST 2.0 Reform Notifications (September 2025); SOIC Research – Decoding India’s AC Industry (2025); IPO Central – Top 10 AC Brands in India (November 2025); ArthaNoVa – How Voltas Became India’s Largest AC Brand (March 2026); CEEW – India Residential Energy Survey (IRES 2020); Data For India – Access to Electricity (September 2024).